You're in a Meridian driveway with a multi-window replacement quote in one hand and a promotional financing page in the other. The monthly figure looks manageable, but the contract total raises a different question: are you choosing an affordable project, or stretching an expensive one far enough into the future that it feels affordable?
That question sits at the center of window replacement financing in Boise. A replacement project can involve a substantial upfront expense, particularly when a home needs several openings upgraded at once. National pricing sources place installed replacement windows at roughly $800 to $2,200 or more per window, while one estimate puts a 20-window project at about $6,000 to $14,000. See the Boise window replacement financing overview from Home Depot for examples of how local and national providers present these offers.
The right financing route should fit your cash flow, payoff plan, home equity, and installation timeline. A low monthly payment isn't automatically a good deal, and a contractor's promotional rate isn't automatically a bad one. The contract details decide that.
Table of Contents
- Why Window Replacement Financing Matters for Boise Homeowners
- Comparing Your Financing Paths in the Treasure Valley
- What You Need Before You Apply
- Reading the Fine Print on Rates and Terms
- Idaho State Programs and Federal Incentives to Stack
- Local Permits, Timing, and Treasure Valley Practical Tips
- Your Next Step With C & C Windows & Doors
Why Window Replacement Financing Matters for Boise Homeowners
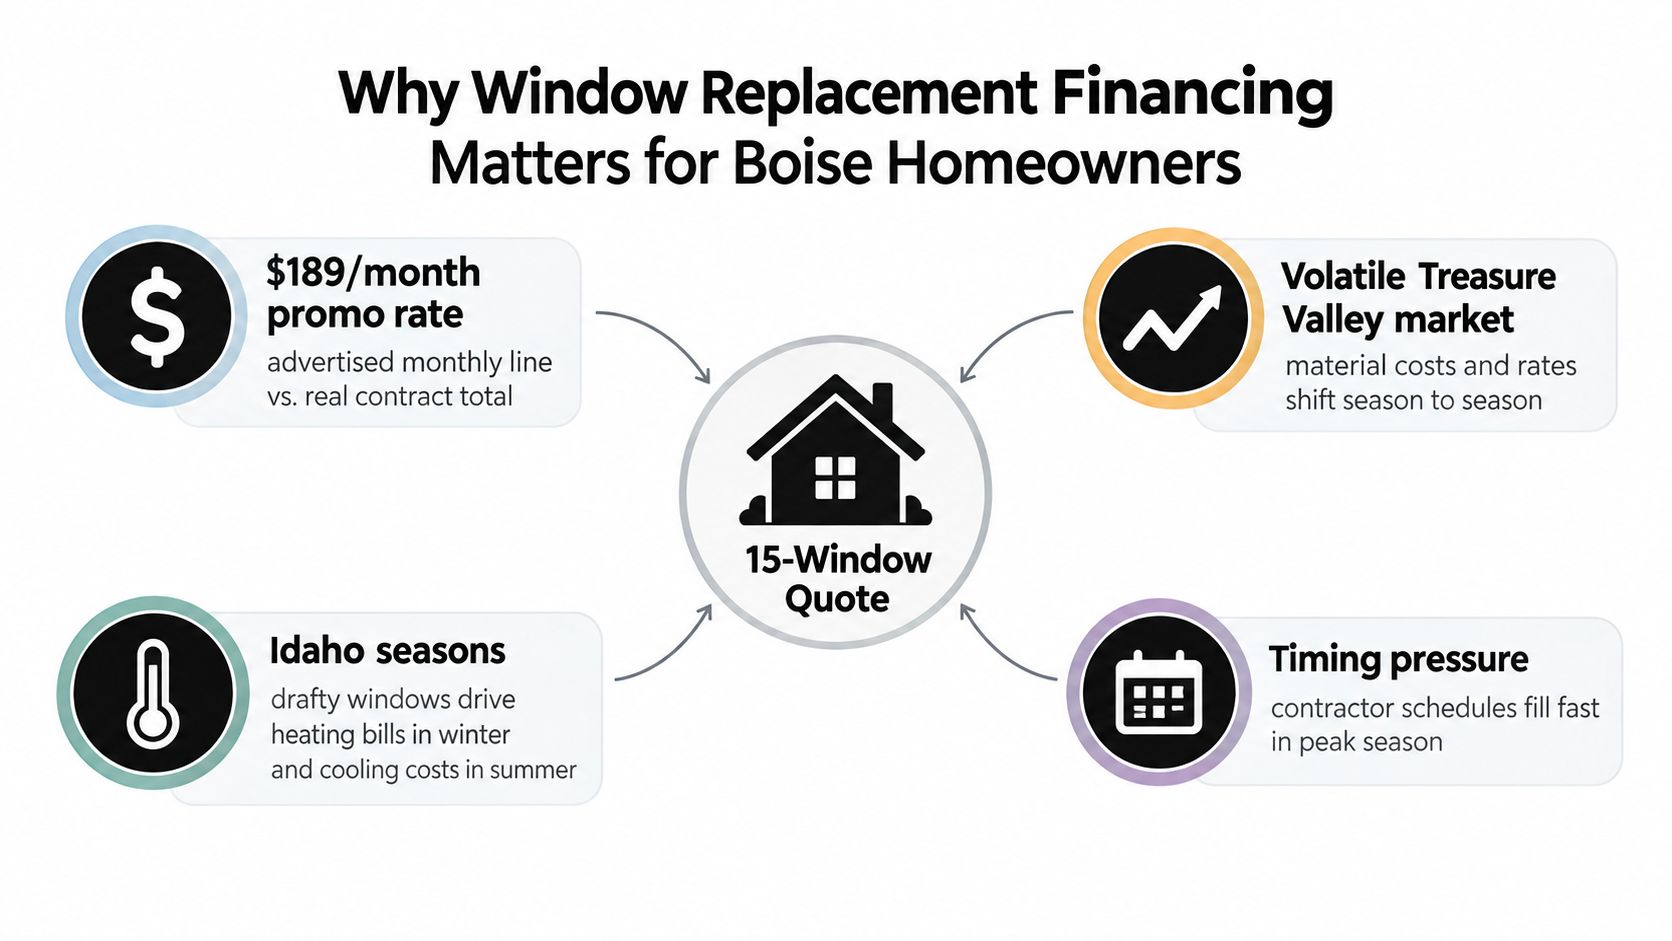
A homeowner in Meridian may start with a simple goal: replace aging windows before another cold winter exposes every draft. Then the quote arrives. The monthly promotional line seems comfortable for a dual-income household, while the full balance feels much harder to absorb. That contrast can push homeowners to focus on the payment instead of the repayment structure.
Treasure Valley homes face demanding seasonal conditions. Winter inversions can make cold, stagnant air settle over the valley, while summer wildfire smoke makes tight seals and dependable operation more noticeable. Older homes, including many built in the 1990s, may also need more than a glass-only insert. Poorly sized openings, deteriorated framing, or water-management concerns can make full-frame replacement the more appropriate scope.
The financing decision can determine whether that larger project fits the household budget. A short promotional period may work for someone with cash reserves and a firm payoff plan. A longer installment loan may suit a homeowner who needs predictable payments, even though the total interest can be higher. A variable home-equity line may offer a lower starting payment but introduce uncertainty later.
The monthly payment is only one number
Local and national providers advertise offers that may include $0 down, 0% interest for a promotional period, and repayment terms extending to 11 years or 180 months. One Boise service page advertises 12 months of special financing alongside financing extending to 180 months, while another Boise-focused provider describes $0 down and 0% interest for 18 months, with financing available for up to 11 years. Those terms can make a major project easier to start, but they don't tell you the total cost by themselves.
Ask what happens after the promotional period. Ask whether interest is waived or merely deferred. Ask how much you must pay each month to clear the balance before the offer expires.
Practical rule: Treat the advertised monthly payment as an entry point, not as the price of the project.
The window brand matters for performance, warranty, and appearance. Financing matters for whether the purchase remains comfortable after the installation crew leaves. Compare both with the same care you give to glass packages, frame materials, and installation scope.
Comparing Your Financing Paths in the Treasure Valley
No single loan fits every Boise-area homeowner. Dealer financing is convenient because the application appears alongside the quote, and approved homeowners may receive promotional terms through contractor financing partners such as Synchrony. The trade-off is that promotional credit can carry strict expiration rules, deferred interest, or a higher post-promotion rate.
An unsecured personal loan separates the borrowing decision from the contractor. It can provide a fixed payment without placing a lien on the home, and some lenders advertise approval and access to funds within 48 hours, loan amounts up to $450,000, terms from 1 to 30 years, and fixed rates as low as 7.8%, as described by HFS Financial's window loan information. Your actual offer depends on credit, income, debt, and lender underwriting.
A HELOC uses available home equity and commonly carries a variable rate. It may provide flexibility for a changing project scope, but payments can rise if the rate changes. A home equity loan generally offers a more defined borrowing structure, though it uses the home as collateral and may involve appraisal and closing steps.
PACE-style financing deserves caution in any Boise comparison. Availability, eligibility, lien treatment, and local program status must be confirmed before you treat it as a real option. Don't let a salesperson place it in the same category as a readily available loan without showing you the governing terms.
Credit cards are the easiest route to use and often the hardest to justify for a large replacement project. Unless the balance will be cleared quickly under a favorable offer, the interest cost can overwhelm the convenience.
Financing path comparison for Boise window replacement
| Financing Path | Typical APR Range | Term Length | Home Equity Required | Key Trade-Off |
|---|---|---|---|---|
| Dealer financing | Varies by promotion and approval | Promotional or installment term | Usually not presented as a home-equity loan | Convenient application, but deferred-interest and post-promotion terms require close review |
| Unsecured personal loan | Varies by lender and credit profile | Lender-specific fixed or variable term | No | Predictable structure without a home lien, but approval and pricing depend heavily on underwriting |
| HELOC | Variable and lender-specific | Flexible draw and repayment structure | Yes | Access to equity and flexibility, with payment and rate risk |
| Home equity loan | Fixed or lender-specific | Fixed lender term | Yes | Defined repayment, but collateral and closing requirements matter |
| PACE-style improvement financing | Confirm current local availability | Program-specific | Property-based obligations may apply | Can differ substantially from consumer loans, so verify lien and resale implications |
| Credit card balance | Card-specific | Revolving | No | Fast access, but potentially expensive if the balance remains unpaid |
The best comparison starts before a contractor frames the discussion around a monthly payment. Get the project scope, then compare dealer credit, a home equity option, and an unsecured personal loan on total repayment, flexibility, collateral, and timing. Guidance from Window Gurus on financing replacement windows recommends securing a written estimate before comparing those funding paths.
What You Need Before You Apply
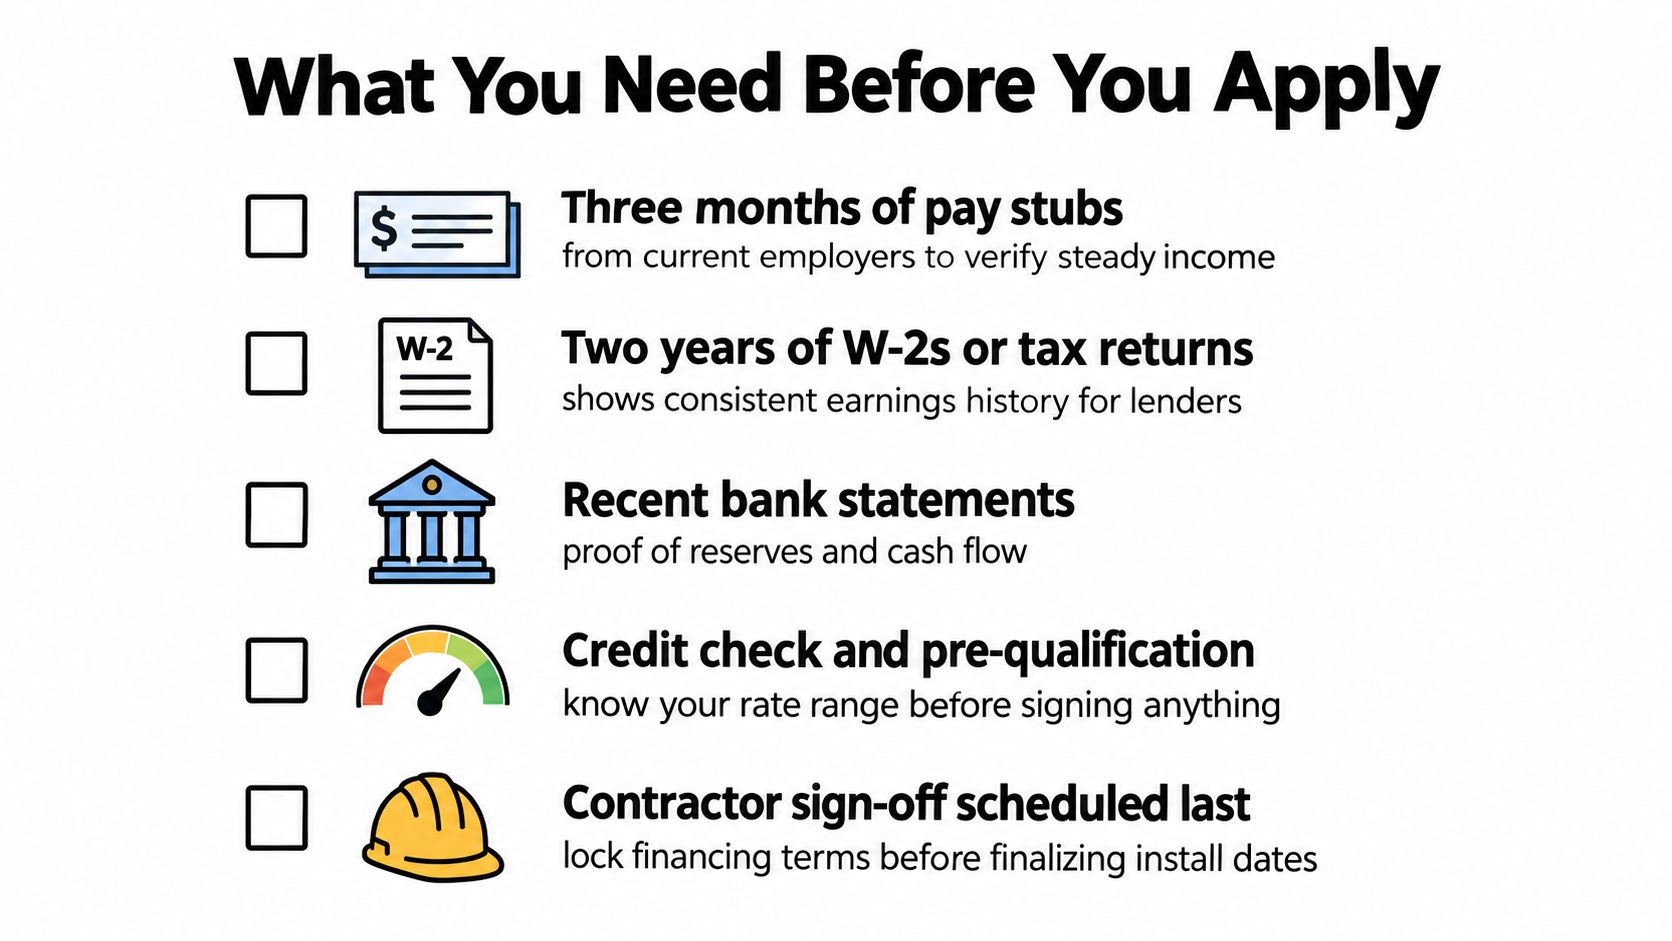
Prepare the financing file before you schedule a final contractor sign-off. Lenders need to understand income, existing obligations, property value, and available cash flow. Having those documents ready also helps you compare offers before installation dates create pressure.
Start with income records:
- Current income: Gather three months of pay information from current employers.
- Earnings history: Self-employed homeowners should prepare two years of W-2s or 1099s, as applicable.
- Property records: Keep recent mortgage statements and property tax records from Ada or Canyon County available.
- Insurance documentation: Include the current homeowners insurance declarations page.
- Cash-flow evidence: Recent bank statements help explain reserves and recurring obligations.
A soft credit pull used for pre-qualification generally lets you review a possible offer without the same effect as a formal application. A hard inquiry occurs when you submit a full application, so ask the lender which type it will use before you authorize the check. HELOC lenders may require a recent appraisal, while dealer financing and personal-loan lenders generally focus more on credit history, income, and debt-to-income information.
Protect your application position
Pull your free annual credit report through AnnualCreditReport.com and dispute errors before applying. If you compare several lenders, ask how they group inquiries and try to submit formal applications within the lender's stated comparison window. The commonly discussed 14-day window should be confirmed with the lender and credit-scoring context involved, rather than treated as a guarantee.
Don't sign the installation agreement first and hope financing catches up later. Use an itemized estimate, confirm the approved amount, and make sure the financing covers the actual scope, including full-frame work, trim, disposal, and any structural changes.
For a project-cost framework before you apply, review how much window replacement costs in Boise. That preparation gives you a better basis for comparing the loan than a payment quote delivered at the kitchen table.
Reading the Fine Print on Rates and Terms
The most dangerous financing clause isn't always the highest advertised rate. It can be the sentence explaining what happens if a promotional balance remains when the offer ends.
Deferred interest is not the same as true 0% interest. Under a deferred-interest offer, the lender may track interest during the promotional period and charge that accumulated amount if you haven't paid the balance in full by the deadline. Paying the minimum can keep the account current while leaving you exposed to a large final charge.
A true comparison requires four figures:
- APR: The annualized cost of borrowing, including applicable finance charges.
- Payment: The amount due under the actual repayment schedule, not only the promotional minimum.
- Term: The number of months before the balance is scheduled to reach zero.
- Total repayment: Principal plus every interest charge and fee.
The requested scenario of a specific project balance, promotional rate, post-promotion rate, personal-loan rate, and HELOC rate can't be responsibly calculated from the verified program information available here. Those figures would produce a false sense of precision if they were treated as an offer available to Boise homeowners. Ask each lender for a written amortization schedule based on your approved amount and exact terms.
Questions that expose the real cost
Read the summary box supplied with the credit offer, including the APR, fees, minimum payment, promotional expiration date, and deferred-interest language. Then ask these questions in writing:
- What happens on the deadline? Does the account charge only future interest, or can it add accrued interest from the beginning?
- What payment clears the balance? Get the required monthly amount, not the minimum.
- Can I prepay freely? Confirm whether any prepayment fee or mandatory payment condition applies.
- What secures the debt? A HELOC or property-based program can affect the home, title, and future sale.
- What changes after the offer? Request the post-promotion APR and the payment calculation.
Longer terms can reduce the monthly burden while increasing the total interest paid. Variable-rate products can change the payment after closing. Buildfolio's window-financing guidance also highlights hidden fees, short repayment windows, cash-flow mismatch, and beginning work before funding is finalized as common risks.
If you're evaluating tax treatment alongside financing, keep the project invoice, product eligibility records, and installation documentation. Use this guide to tax credits for replacement windows as a starting point, then verify current rules with a qualified tax professional.
Idaho State Programs and Federal Incentives to Stack
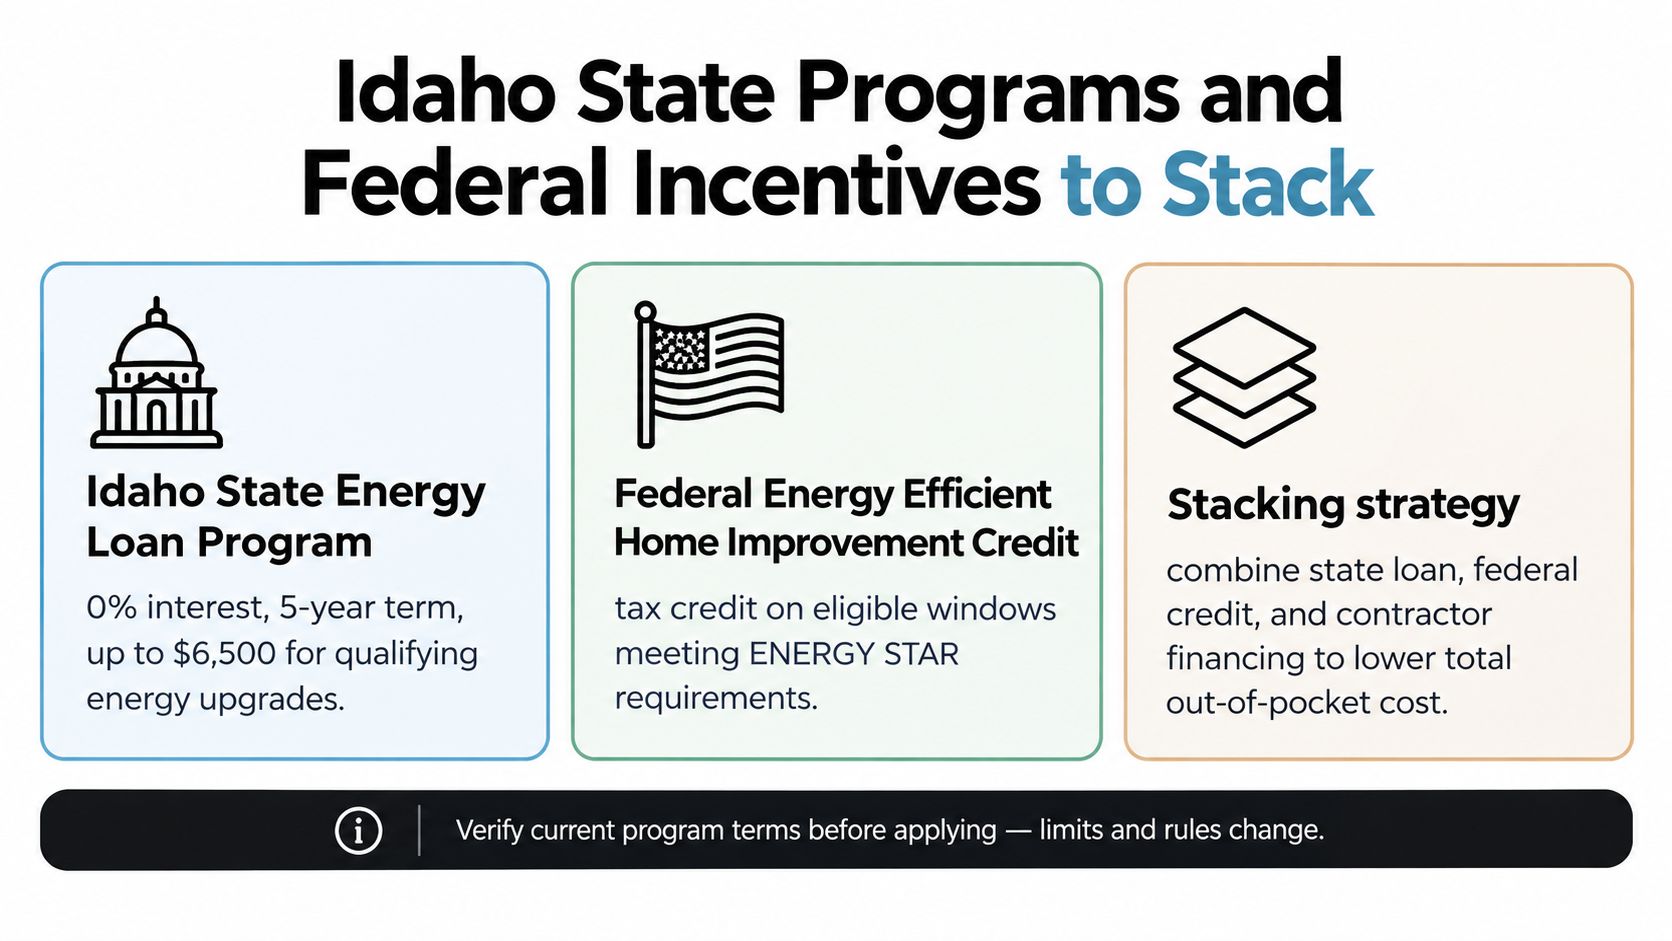
A dealer-financing promotion is not automatically the cheapest way to fund Boise window replacement. Compare it with the Idaho State Energy Loan Program before signing, especially if the contractor offer defers interest until a promotional deadline. Missing that deadline can add accrued interest to the balance, while a fixed state loan gives you a payment schedule from the start.
The Idaho program covers window and door replacements, does not use an income test, and offers fixed low-rate options tied to real-estate-secured loans. Current terms are listed as 3%, 5%, or 7%, depending on term length. It is listed as active through December 31, 2026, according to the Idaho Office of Energy and Mineral Resources loan program as of September 2026.
The trade-off is timing. The state loan must be approved and funded before installation begins. If your project needs to start immediately, dealer financing or another route may fit better. If you can wait for approval, the fixed structure can cost less than a promotional account that changes after the offer ends. Check current utility incentives with the Idaho Power window rebate guide before stacking them with the state loan.
Federal incentives can reduce the remaining balance. The Energy Efficient Home Improvement Credit allows a 30% credit for qualified energy-efficiency improvement costs for eligible products installed through December 31, 2025. The general yearly cap is $1,200 for many home-envelope improvements, with a separate $600 window and skylight cap. Windows must meet ENERGY STAR Most Efficient criteria. Use the IRS guidance on the Energy Efficient Home Improvement Credit for the governing details.
Check eligibility before counting the credit
The federal window credit applies to an existing home in the United States that the taxpayer owns and uses as a primary residence. It does not apply to new construction, renters, or second homes, and the taxpayer must file Form 5695. Confirm product eligibility before ordering. A low financing rate cannot make an ineligible window qualify.
Idaho's energy office says consumers may combine state loans with utility incentives and federal or state credits or deductions. It also directs low-income households toward year-round Weatherization Assistance. Review the Idaho incentives and financial information before assigning a rebate or credit to your budget.
The Department of Energy describes the HOMES rebate program as potentially providing up to $8,000 for projects that significantly reduce household energy use. It may fit a broader efficiency package better than an isolated window replacement. Verify project requirements, administration, and timing before borrowing against an expected rebate. Use incentives to reduce a confirmed balance, not to justify a loan you cannot comfortably carry.
Local Permits, Timing, and Treasure Valley Practical Tips
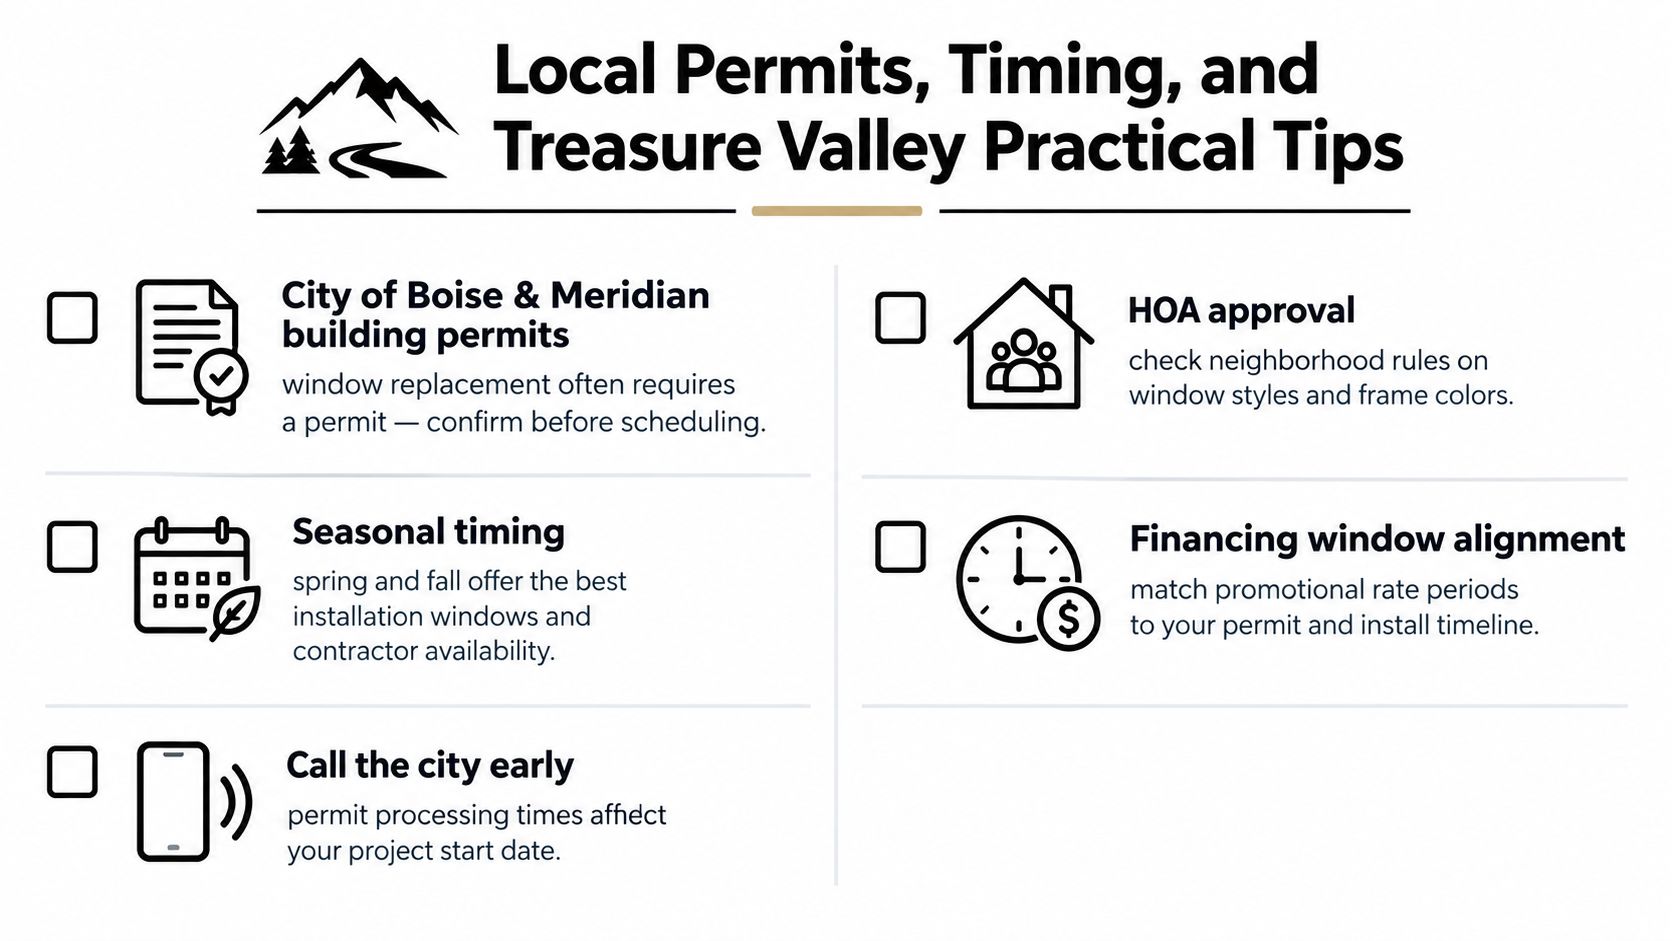
Financing should follow a confirmed project scope, not lead it. A permit change, HOA rejection, or installation delay can push a promotional deadline closer while your balance remains outstanding.
City of Boise and Meridian permit requirements can apply when window replacement changes structural framing. Like-for-like replacements in existing openings may follow a simpler review path, but the homeowner should confirm the requirement with the relevant jurisdiction before scheduling work. Don't rely on a salesperson's assumption when the scope includes altered openings, new headers, or other structural work.
Homeowners in Eagle and North Boise subdivisions should also check HOA rules for frame color, divided-light patterns, exterior appearance, and architectural review. Approval can add 30 to 45 days in some neighborhood processes, so request the written review timeline before you accept an installation date.
Match the funding clock to the project clock
Idaho Power HOMES rebate waitlists may be busiest from February through April, while contractor schedules can fill fastest from August through October. These seasonal patterns make timing important, but they don't justify rushing into an unsuitable loan.
Use this order:
- Confirm the scope: Decide whether the work is insert replacement, full-frame replacement, or a broader opening modification.
- Check the jurisdiction: Ask Boise or Meridian whether a permit and inspection apply.
- Review HOA requirements: Submit architectural materials before committing to a start date.
- Verify incentive rules: Confirm eligibility and whether approval is needed before installation.
- Lock the financing: Finalize the rate and amount after the scope and permit path are stable.
A rate locked against an unapproved scope may need to be reviewed again when the work changes.
That sequence protects the household from borrowing for a project that can't start on time. It also gives you a stronger position when a contractor says the promotional offer expires soon.
Your Next Step With C & C Windows & Doors
The phrase “sign today to lock in the promotion” should never replace a complete cost comparison. A calm Boise homeowner can request a written, itemized quote from C & C Windows & Doors, then ask which Synchrony or Hearth terms apply to the specific project scope. The lender's name matters less than the written APR, repayment schedule, fees, collateral terms, and treatment of deferred interest.
Ask whether the quoted price assumes any federal Energy Efficient Home Improvement Credit or HOMES rebate assignment. A contractor shouldn't present an expected tax benefit as an immediate discount unless the paperwork and eligibility support that treatment. You should also verify whether the installation window fits the City of Boise or Meridian permit timeline and any HOA review period.
Questions to put in writing
- Deferred interest: Is the offer true 0% interest, or can accrued interest be charged if the balance remains?
- Payoff amount: What exact payment clears the balance before the promotional deadline?
- Prepayment: Can you pay early without a penalty or special condition?
- Lien requirements: Does the financing place any claim against the property?
- Scope changes: What happens if permits, measurements, or framing alter the quote?
- Installation timing: Does the proposed schedule leave enough time for approval and funding?
- Incentive treatment: Which credits or rebates belong to the homeowner, and which documents will be provided?
Get two competing Treasure Valley quotes, compare the same window performance and installation scope, and take a 48-hour cool-off period before signing. That short pause can expose a missing disposal charge, an unrealistic payoff schedule, or a promotional deadline that doesn't match your cash flow.
C & C Windows & Doors offers free in-home consultations, custom measurements, replacement windows and patio doors for Treasure Valley homes, and Synchrony financing for approved applicants. Treat those services as part of your comparison process, not as a reason to skip lender review.
C & C Windows & Doors can help you build an itemized replacement-window plan, review available financing options, and align the installation scope with your Boise-area home. Book a consultation through C & C Windows & Doors and bring your financing questions, permit concerns, and incentive paperwork to the conversation.